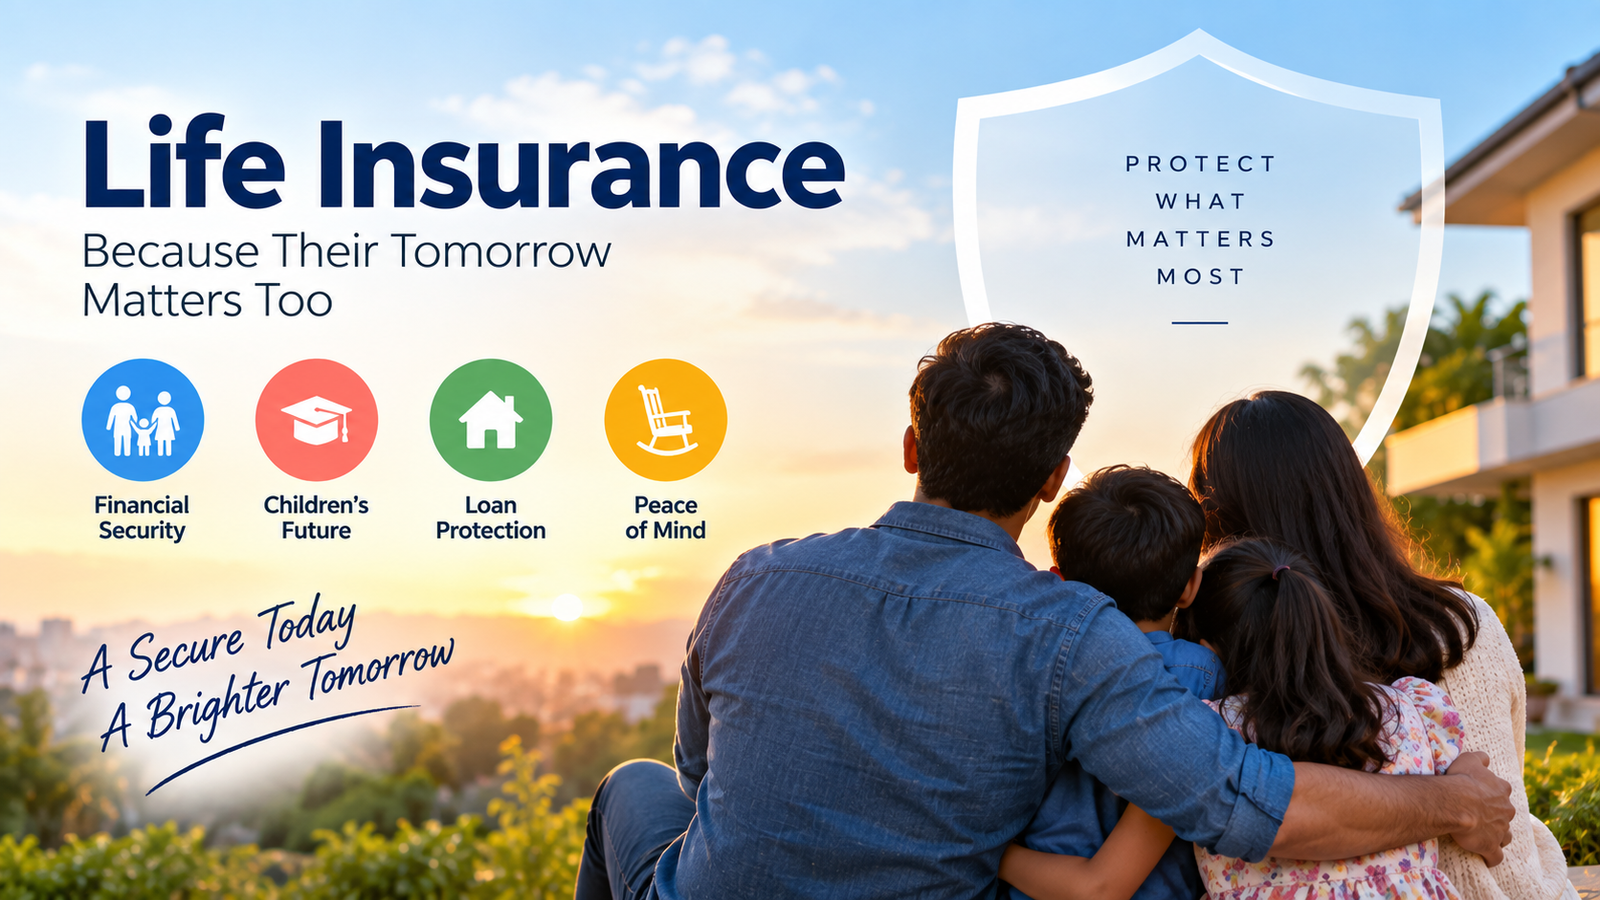
Life is full of uncertainties, but financial planning can help you prepare for them. Life insurance is one of the financial protection tools that can help provide financial support to your family if something happens to you during the policy period.
Whether you are the primary earning member of your family, have outstanding loans, or want to create a financial safety net, understanding how life insurance works can help you make a more informed decision.
What Is Life Insurance?
Life insurance is a contract between an individual and an insurance company. The policyholder pays a premium according to the policy terms, and the insurer provides specified benefits based on the coverage selected.
In many life insurance policies, if the insured person dies during the covered period, the insurer pays a death benefit to the nominee, subject to the policy’s terms and conditions.
Different types of life insurance can have different features, benefits, premium structures, and maturity provisions.
Why Is Life Insurance Important?
The primary purpose of life insurance is financial protection. If your family depends on your income, an unexpected loss of income can create significant financial pressure.
Life insurance can help provide financial support for goals such as:
- Household expenses
- Children’s education
- Outstanding loans and liabilities
- Future financial planning
- Long-term family security
- Other financial commitments
The actual benefit depends on the policy selected and its terms.
How Does Life Insurance Work?
The process is generally straightforward:
1. Choose Your Coverage
You select a policy based on your financial responsibilities, desired coverage, policy duration, and other requirements.
2. Pay the Premium
You pay the premium according to the payment frequency and terms specified in the policy.
3. Keep the Policy Active
Premiums generally need to be paid as required to maintain the policy according to its conditions.
4. Claim or Maturity Benefit
Depending on the policy type, the insurer may provide a death benefit to the nominee if the insured event occurs, or a maturity benefit may be available if the policy includes one and the policy reaches maturity.
Always check the specific policy wording because benefits vary between products.
Common Types of Life Insurance
Term Life Insurance
Term insurance provides life cover for a specified period. If the insured person dies during the policy term, the nominee may receive the applicable death benefit.
Term insurance is generally structured primarily around protection rather than savings.
Whole Life Insurance
Whole life insurance is designed to provide coverage for a much longer period, subject to the policy’s terms and conditions. Some products may also include additional features or benefits.
Endowment Plans
Endowment policies can combine insurance protection with savings. Depending on the policy, a maturity benefit may be payable if the policyholder survives the policy term.
ULIPs
Unit Linked Insurance Plans, commonly known as ULIPs, combine insurance protection with investment components. A portion of the premium may be allocated to investment funds after applicable charges and deductions.
Returns are linked to the performance of the selected funds and are therefore subject to market-related risks.
How Much Life Insurance Cover Do You Need?
There is no single coverage amount that works for everyone.
When evaluating your coverage requirement, consider:
Current income: How much financial support would your family need if your income stopped?
Outstanding liabilities: Include home loans, personal loans, education loans, or other significant debts.
Future goals: Consider children’s education, marriage expenses, retirement planning for dependents, and other long-term goals.
Existing savings and investments: Your current assets can also influence the amount of insurance coverage you may need.
A useful approach is to calculate your family’s financial needs rather than selecting a policy only because of its premium.
Factors to Consider Before Buying Life Insurance
Policy Coverage
Understand exactly what events and benefits are covered.
Premium
Compare the premium with the coverage and policy duration. A lower premium does not necessarily mean the policy is more suitable for your needs.
Policy Term
Choose a term that aligns with your major financial responsibilities and family goals.
Claim Process
Understand the documentation and procedure required to make a claim.
Exclusions and Conditions
Read the policy documents carefully to understand exclusions, waiting periods where applicable, conditions, and other limitations.
Nominee Details
Keep nominee information updated so that the intended beneficiary details are correctly recorded with the insurer.
When Should You Consider Buying Life Insurance?
Life insurance is often considered when someone has financial dependents or significant long-term financial responsibilities.
Important life events that may prompt a review of insurance needs include:
- Starting a family
- Getting married
- Purchasing a home
- Taking a significant loan
- Having children
- Starting a business
- Experiencing a major change in income
Your insurance requirements can change over time, so reviewing your coverage periodically can be useful.
Final Thoughts
Life insurance can play an important role in a broader financial protection strategy. The right policy depends on your income, financial responsibilities, dependents, goals, budget, and the specific terms of the insurance product.
Before purchasing a policy, compare the coverage, premium, policy duration, exclusions, benefits, claim process, and conditions carefully. Don’t choose a policy based only on price.
A well-planned life insurance policy can help create a financial safety net for the people who depend on you when they need it most.